Will homeowners insurance cover foundation repair
Scenario-by-scenario answers on whether a homeowners policy pays for foundation repair, plus the evidence that decides a claim.
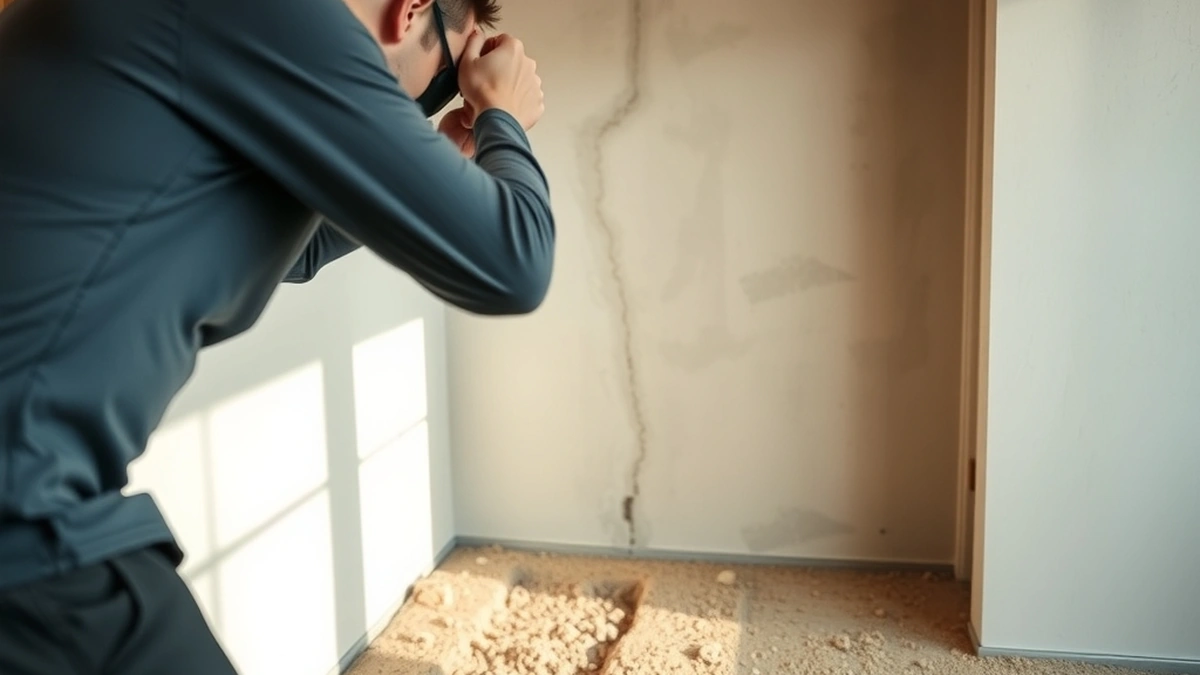
Homeowners insurance will cover foundation repair when a sudden covered event caused it, such as a burst pipe, fire, or vehicle impact. It will not cover settlement, earth movement, or long-term drainage, which are excluded on standard policies.
- Burst pipe damage
- Usually covered
- Settlement
- Usually denied
- Earthquake
- Separate coverage needed
- Engineer report
- $400 - $1,500
- Typical repair
- $4,000 - $15,000
Some links on this page are affiliate links.If you buy through them we may earn a commission at no extra cost to you. We do not accept payment for rankings. Read the full disclosure.
Will homeowners insurance cover foundation repair? It depends on one thing: whether a covered event caused the damage. A burst pipe, a fire, or a vehicle strike usually qualifies. Settlement, soil movement, and years of poor drainage do not, because standard policies exclude them by name. The scenarios below show where that line usually falls.
The general rule in one paragraph
A homeowners policy covers the structure against listed perils and excludes a list of causes. Foundation damage is a result, so the adjuster traces it to a cause. Sudden and accidental causes are usually covered. Gradual causes, earth movement, and maintenance failures are usually excluded. The policy language controls, and it varies by state and by form, so read the exclusions section before filing.
Five scenarios and how they end
| Scenario | Likely outcome | Reason |
|---|---|---|
| Supply pipe bursts under the slab | Covered | Sudden water escape is a covered peril |
| Foundation settles over ten years | Denied | Earth movement and settling are excluded |
| Tree root heaves a driveway slab | Usually denied | Earth movement and maintenance |
| Vehicle hits the foundation wall | Covered | Sudden accidental impact |
| Storm runoff erodes the footing | Often denied | Water damage and earth movement exclusions |
| Fire damages the foundation | Covered | Fire is a named peril |
Two of those outcomes are close calls. Storm runoff can be covered if the policy includes water damage from a sudden event rather than seepage, and an erosion claim sometimes depends on whether the loss is classified as flood. That is a conversation for the adjuster and the policy wording, not a guess.
The burst pipe case, in detail
This is the claim most likely to succeed, so it is worth understanding how it is built.
A copper supply line under a slab develops a pinhole leak and eventually fails, and water lifts a section of the slab. The plumber documents the failure, the slab is opened, and the line is repaired. The policy typically pays for the access, the pipe repair, and the restoration of the concrete and flooring.
What the policy usually does not pay for is the pre-existing corrosion. The failure is covered; the maintenance that led to it is not. That distinction shows up in the adjuster’s report and in the settlement amount.
The engineer’s letter should say the slab damage is consistent with the water escape on the plumber’s report. That single sentence links the covered cause to the foundation damage.
Evidence that decides a claim
- A dated cause-and-origin report from a structural engineer, typically $400 to $1,500.
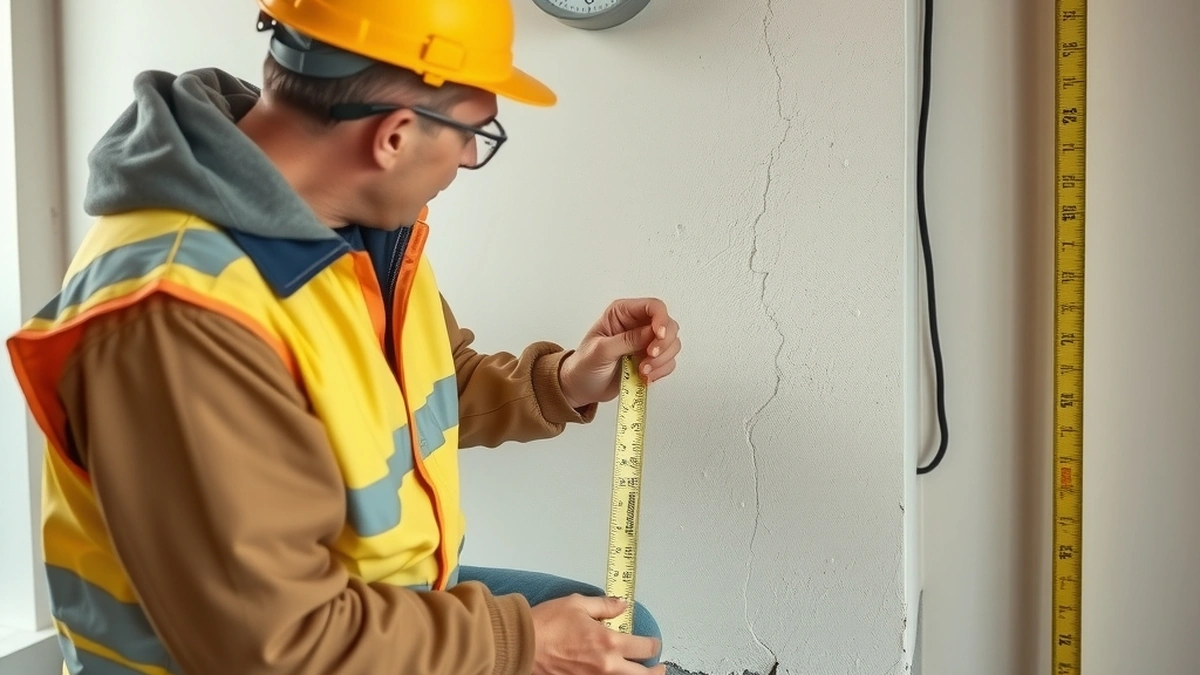
- Photographs of the damage before any cleanup, with a ruler or gauge in frame.
- Photographs from before the event, which show the wall or slab was intact.
- Plumbing or mechanical reports naming the failed component and the date.
- A repair estimate broken into piers, square footage, engineering, and restoration.
- A written log of calls, visits, and emails with the claim number.
The estimate matters less than the cause. Homeowners often lead with the repair number, which invites a coverage argument before the cause is settled. Lead with the cause and let the number follow.
What the policy will not do
It will not pay to fix maintenance that should have been done. Gutters that discharged at the wall for a decade are a maintenance failure, and the resulting settlement is excluded.
It will not pay for a crack that was visible when you bought the house and disclosed in the sale. Prior damage is generally not a new loss.
It will not pay for cosmetic repair alone. If the crack is stable and the repair is patching, the cost usually falls below the deductible anyway. With typical deductibles, a $2,000 patch is a homeowner expense.
It will not cover earth movement unless you bought the endorsement or a separate policy. Earthquake coverage is sold separately in every state, and sinkhole coverage is an endorsement in some.
When the insurer says no
Ask for the denial in writing and read the cited clause. Then decide whether the cause is genuinely excluded or whether the adjuster has misclassified it.
If the cause is arguable, request a re-review with new evidence: a second engineer’s opinion, the plumber’s report, or photographs that establish the date. A re-review is not an appeal, and it is often enough to move a file.
If the denial stands, file a complaint with the state insurance department. The complaint is free, it creates a record, and it usually produces a written response from the carrier.
Do not authorize repairs before the claim is resolved unless the damage is unsafe. A completed repair with no adjuster inspection is much harder to recover.
What to do before you file
Measure the crack and photograph it. Read the exclusions. Call the agent and ask whether the cause is covered, without filing yet. Get the engineer report if the cause is unclear.
That sequence protects the claim and protects the premium. A denied claim still appears in the record, and too many of them can affect renewal.
For the coverage categories and endorsements, see is foundation repair covered by insurance. For the repair pricing behind a claim, foundation repair cost has the bands. If the loss involves a plumbing failure, foundation leak repair explains the repair order.
Bottom line
Homeowners insurance will cover foundation repair when a sudden covered event caused it and will deny it when the cause is settlement or earth movement. Build the claim around the cause, document the date, and keep the denial in writing if it comes.
Frequently asked questions
Will my policy cover a cracked foundation?
Only if a covered event caused the crack. A crack from settling or soil movement is generally excluded as a maintenance item.
Does a burst pipe under the slab get covered?
Usually yes. The sudden water escape is a covered peril, and the policy typically pays for access, pipe repair, and slab restoration.
Will insurance cover foundation repair after a flood?
Only if you hold flood coverage, and even then the policy addresses inundation damage rather than later settlement.
What evidence does an adjuster need?
A dated cause-and-origin engineer report, photographs before and after, plumbing records, and a repair estimate broken down by line.
Can I appeal a denied foundation claim?
Yes. Ask for the denial in writing with the clause cited, submit additional evidence, and escalate to the state insurance department.
Does a denied claim affect my premium?
A claim is usually recorded even when denied, so file only when the cause is plausibly covered and the documentation supports it.
Sources
Some links are affiliate links.If you buy through them we may earn a commission at no extra cost to you. We do not accept payment for rankings. Read the full disclosure.